Key Takeaways:
- A total-loss settlement usually begins with the vehicle’s actual cash value immediately before the crash.[1]
- Mileage, trim, options, condition, location, and comparable vehicles can affect the valuation.
- Review the full report, not only the final offer amount.
- Correcting a wrong trim, missing option, mileage entry, or condition deduction may change the result.
- Local listings and clear documentation can support a request for a revised valuation.
- Deductibles, taxes, fees, loan balances, and appraisal rights can affect the amount ultimately paid.
What a Total-Loss Valuation Measures?
When an insurer determines that a vehicle is a total loss, its offer commonly reflects the car’s actual cash value, meaning its market value shortly before the collision. That figure is not necessarily the original purchase price, the replacement cost of a new vehicle, or the amount remaining on an auto loan.
A CCC One valuation report can show how an insurer arrived at its number, including the comparable vehicles, adjustments, and condition assumptions used in the calculation. Reviewing those inputs is often more useful than debating the settlement figure on its own.
The vehicle’s value differs from the final payment. A deductible may apply under a first-party collision claim, and state-specific rules may affect whether taxes, title charges, registration costs, or transfer fees are included. For a broader explanation, actual cash value in auto insurance generally reflects depreciation and the vehicle’s condition before the loss.
The Main Parts of a Valuation Report.
Read the report line by line. A typical valuation includes the vehicle identification number, year, make, model, trim, recorded mileage, factory equipment, condition description, comparable listings, and dollar adjustments for differences among vehicles. It may also show taxes, fees, deductibles, and any salvage deduction if the owner keeps the vehicle.
Start With the Vehicle Description.
Confirm that the report describes the exact vehicle that was lost. A seemingly minor mismatch can matter if it changes the trim, drivetrain, engine, body style, or equipment package. Keep the registration, title, original window sticker, purchase records, and service records nearby while reviewing them.
How to Review Comparable Vehicles?
Comparable vehicles should be reasonably similar to the totaled car. Review each one for model year, trim, mileage, drivetrain, engine, transmission, body style, condition, and location. Also, check that the listing was active close to the date of loss, rather than months earlier.
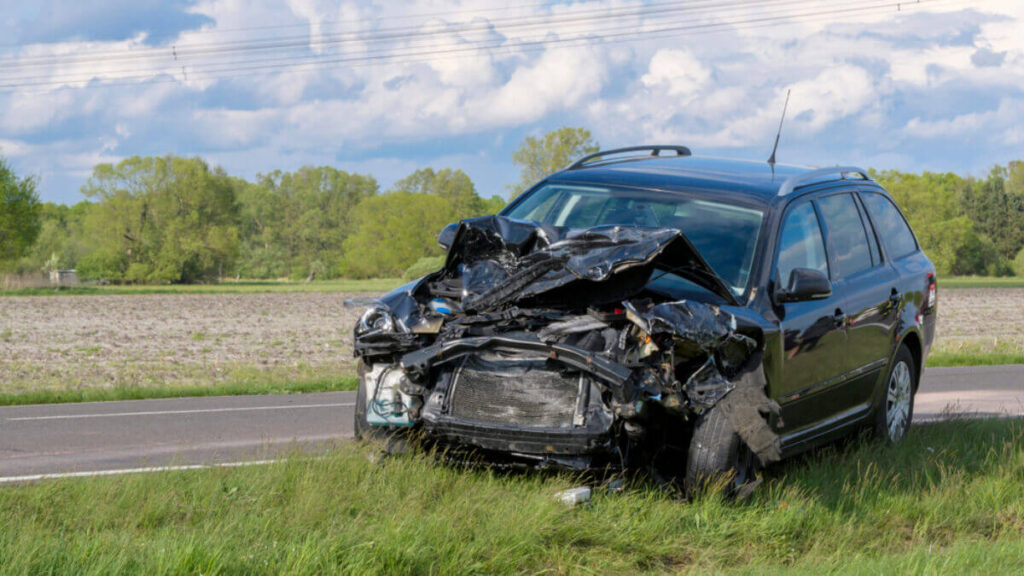
For example, an all-wheel-drive premium trim should not be treated as identical to a base front-wheel-drive version unless the report makes an appropriate adjustment. The same concern applies when a comparable has substantially higher mileage or lacks major equipment.
Checking Mileage, Trim, and Options.
Incorrect mileage, trim, and options can quietly reduce a valuation. Compare reported mileage with recent repair invoices, inspection records, dealership service history, or photographs of the odometer. Confirm the trim through the vehicle identification number, window sticker, or manufacturer documentation when available.
Then look for omitted features, such as driver-assistance packages, navigation, towing equipment, leather seating, premium audio, roof systems, or upgraded wheels. Receipts for recent maintenance do not automatically add their full cost to the value, but they can help show that a claimed mechanical or condition problem was not present before the loss.
Reviewing Condition Adjustments.
Condition adjustments deserve close attention. Identify deductions for dents, scratches, tire wear, interior damage, mechanical issues, or prior repairs. The report should distinguish pre-existing wear from collision damage, because accident damage should not be counted as a pre-loss condition problem.
Use dated photos, inspection reports, maintenance files, and prior appraisals to challenge a condition description that does not match the vehicle’s actual pre-crash state. Focus on documented facts. A car need not be flawless to be accurately described as average or better maintained.
Why Local Market Data Matters?
A valuation should reasonably reflect the market where the owner would replace the vehicle. Search within a practical driving area for close matches, then save screenshots that show the listing date, dealer or private seller, location, price, mileage, trim, and options. Asking prices are not completed-sale prices, but closely matched current listings can still help identify weak comparisons.
Rules vary by state. Washington’s insurance regulator, for example, explains that insurers may use comparable local vehicles and that consumers can ask for a total-loss valuation report. Its guidance for a totaled car also notes that appraisal provisions may be available when a valuation dispute cannot be resolved. Requirements differ by state and policy.[2]
Checking the Settlement Math.
Follow the calculation from beginning to end:
- Adjusted vehicle value
- Plus applicable taxes and transfer-related fees
- Minus the policy deductible, if applicable
- Minus any salvage value if the owner retains the vehicle
- Equals the estimated settlement payment
A loan payoff is separate from the car’s value. If the loan balance exceeds the settlement amount, gap coverage may cover some or all of the difference, depending on its terms. Ask the insurer and lender how payment will be handled before agreeing to a settlement.[3]
Building a Clear Counteroffer.
- Request the complete valuation report.
- Mark each incorrect fact or unsupported deduction.
- Find closer local comparable vehicles.
- Write a short explanation of every requested correction.
- Attach photos, records, receipts, and saved listings.
- Ask for a written response and revised valuation.
A strong response is calm and specific. State what is wrong, explain why it affects value, and provide evidence that lets the adjuster verify the correction.
When an Appraisal Clause May Help?
Some auto policies include an appraisal clause for disputes about vehicle value. The process may involve appraisers selected by the policyholder and the insurer, plus an additional person if the appraisers disagree. Costs, deadlines, and procedures vary, so read the exact policy language first. An appraisal process generally addresses value, not fault, coverage disputes, or injury claims.
Common Mistakes to Avoid.
- Accepting the first offer without asking for the report.
- Using only broad online price estimates instead of close vehicle comparisons.
- Submitting listings with a different trim, drivetrain, or major equipment.
- Failing to save listings before they disappear.
- Overlooking deductibles, lien payoff details, or salvage deductions.
- Sending a long emotional message instead of an evidence-based request.
A Five-Minute Review Checklist.
- Is the year, make, model, trim, and mileage correct?
- Are major factory options included?
- Are the comparable vehicles genuinely similar and locally relevant?
- Does pre-loss evidence support the condition deductions?
- Are applicable taxes and fees addressed?
- Is the deductible correct?
- Does the policy contain an appraisal provision?
Conclusion.
A total-loss valuation should receive more than a quick review of its final number. Checking the underlying data can reveal incorrect mileage, a missing option package, weak comparable vehicles, unsupported condition deductions, or overlooked fees. A well-organized response, backed by local market evidence, can help a vehicle owner make an informed decision before accepting an insurance offer.
References:
[1] National Association of Insurance Commissioners (NAIC). Consumer Auto. The NAIC explains that an insurer may total a vehicle when repair costs quickly exceed its worth and that the insurer generally pays what the vehicle was actually worth immediately before the crash, based in part on comparable vehicles in the local area. Consumer Auto.
[2] Washington State Office of the Insurance Commissioner. What happens after your car gets totaled. The guidance explains actual-cash-value settlements, comparable vehicles in the local area, total-loss valuation reports, taxes and fees, and appraisal options when applicable. What happens after your car gets totaled.
[3] Consumer Financial Protection Bureau. What is Guaranteed Asset Protection (GAP) insurance? March 8, 2024. The CFPB explains that GAP is an optional product intended to cover the difference between the amount owed on an auto loan and the amount paid by insurance when a vehicle is stolen or totaled, subject to the product’s terms and restrictions. What is Guaranteed Asset Protection (GAP) insurance?

Leave a Reply